October 2, 2026 - CALGARY REAL ESTATE UPDATE
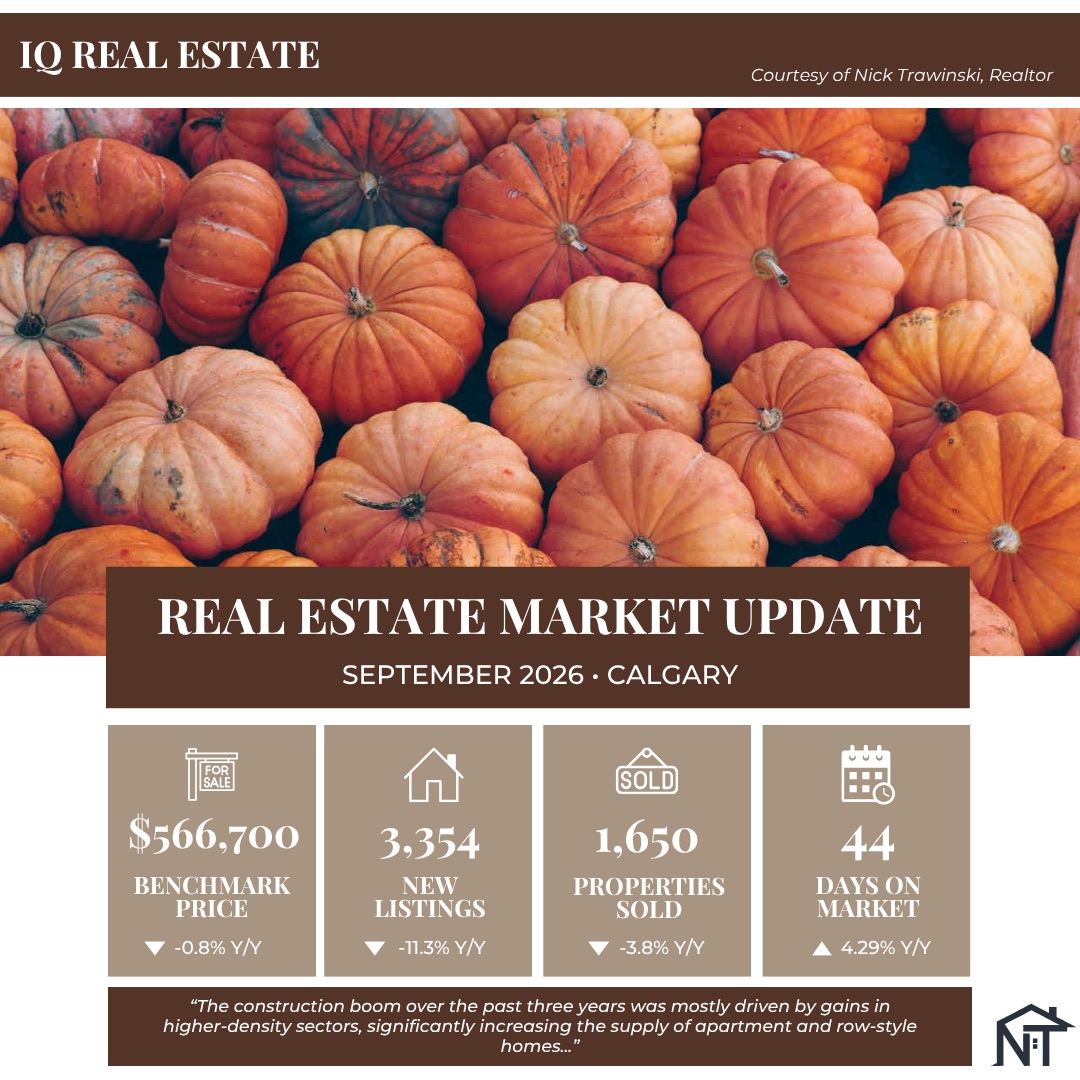
September sales totalled 1,650 units, similar to August and nearly 4% lower than in September 2025. While September sales typically pull back compared with August, stronger detached home sales helped prevent the typical seasonal pullback.
At the same time, new listings also rose from August, causing the sales-to-new-listings ratio to fall to 49%, leaving inventory levels relatively stable compared with August. Stable sales and inventory levels in September prevented any change in the months of supply compared with August, which remained at just under four months.
While the overall market is showing higher supply levels compared with sales activity, conditions vary significantly by property type. Detached properties remain in balanced territory, and the monthly boost in new listings supported gains in sales in September. Meanwhile, higher supply levels for apartment and row homes are contributing to buyer market conditions, as demand is spread across more alternatives in the rental and new home markets.
“The variation in market conditions between property types is related to where the supply was added. The construction boom over the past three years was mostly driven by gains in higher-density sectors, significantly increasing the supply of apartment and row-style homes,” said Ann-Marie Lurie, Chief Economist at the Calgary Real Estate Board (CREB®). “Meanwhile, detached homes did not see the same boost in construction, preventing broad-based supply growth. Thanks to a stronger job market and slower but positive net migration, housing demand has remained strong enough to absorb some of the supply, but not enough to offset the high-density supply added to the market, resulting in a more significant impact on prices for higher-density homes.”
As the market moves through the fall, it is not unusual to see some unadjusted monthly declines in prices. However, many of these adjustments were seasonal, as seasonally adjusted figures show that prices in September are relatively stable compared with August. The unadjusted residential benchmark price was $566,700, nearly 1% lower than last year. Most of the price adjustments have occurred in higher-density row and apartment-style units, which have reported year-over-year declines of 8% and 6% in September. Meanwhile, detached prices are 1% lower than last year, mostly due to declines in the North East, East and North districts.
NICK’S TAKE
Calgary’s September market remains highly dependent on the property type and area of the city, with detached homes holding up better while higher-density properties continue to face more supply pressure.
- Detached homes remain relatively balanced, with sales improving from August and increasing year-over-year. Conditions are tighter in the North West, West, and South, while the North East continues to carry significantly more inventory.
- Townhomes and apartment condos remain the softer segments of the market. Townhome inventory has climbed above four months of supply, while apartments remain above five months, giving buyers more options and contributing to further year-over-year price declines.
- Pricing and location continue to matter significantly for sellers. While overall benchmark prices have remained relatively stable month-over-month after accounting for seasonality, higher-density properties and oversupplied areas are seeing more downward pressure. Sellers need to price closely to current market conditions, while buyers may have more negotiating leverage in segments with elevated inventory.
DETACHED — BALANCED MARKET
Sales in September reached 896 units, up from August and more than 4% higher than last year. The improvement in sales was partly due to a boost in new listings in September compared with August, giving consumers more options. With a sales-to-new-listings ratio of 52% and a months of supply at just over three months, conditions remained relatively balanced. However, conditions have varied across the city, with less than three months of supply in the North West, West and South districts, and nearly six months of supply in the North East district.
While the overall market is relatively balanced, the unadjusted benchmark price was 1% lower than last year. The decline was primarily driven by steep pullbacks in the oversupplied North East district. Meanwhile, prices were higher than last year in both the City Centre and West districts.
SEMI-DETACHED — BALANCED MARKET
The year-over-year gain in sales was not enough to offset earlier declines, as year-to-date sales have declined by 2% for a total of 1,678 sales. The decline in sales matched year-to-date declines in new listings, but a monthly boost in September listings caused the sales-to-new-listings ratio to dip to 45%, contributing to monthly inventory gains and pushing months of supply to nearly four months. While this is a shift from the tighter conditions reported in this sector throughout most of 2026, it is too early to say whether this will continue into the final quarter.
While unadjusted prices did trend down in September, much of the decline was in line with typical seasonal behaviour. The unadjusted September benchmark price was $685,200, comparable to levels reported last year at this time.
ROW/TOWNHOME — BUYER’S MARKET
Sales in September eased compared with August, while new listings rose, causing the sales-to-new-listings ratio to drop to 45%. This also contributed to higher inventory levels compared with both last year and August, resulting in the months of supply rising above four months for the first time since the beginning of the year.
Additional competition from new units has weighed on resale activity, as the price spread between new and resale homes remains relatively narrow. The additional supply choice for buyers has also weighed on row prices, but not to the same extent as in the apartment sector.
As of September, the unadjusted benchmark price was $412,400, down nearly 6% from last year. While prices have declined across all districts, the steepest declines, at more than 11%, have occurred in the North East and East districts, while the smallest declines have occurred in the North West, at 2%.
APARTMENT/CONDOMINIUM — BUYER’S MARKET
Apartment sales improved from August, slowing the year-over-year pace of decline to 14%. New listings also rose over August, with 343 sales and 717 new listings, leaving the sales-to-new-listings ratio at 48%. The monthly gains in sales supported modest reductions in inventory levels and prevented any further increases in the months of supply, which remained just above five months.
The excess supply of apartment-style units has weighed on prices throughout most of the year. As of September, the unadjusted benchmark price fell to $291,400, down more than 1% compared with August and more than 8% lower than last September. While some of the monthly decline is seasonal, seasonally adjusted prices continued to decline.
Source: CREB® September 2026 housing market report. Market figures are reported as of September 2026.